How to Help Your New Driver Understand Auto Insurance
This informational blog is not legal advice. Always consult a qualified DUI attorney to assist with legal questions. If you have immediate questions about SR-22 insurance, call a Breathe Easy licensed insurance agent at (833) 786-0237.
Earning a driver’s license is an exciting step for new drivers, but it comes with certain responsibilities to help avoid behavior-based insurance penalties.
Teens may focus on the excitement and freedom of driving, but insurance plays a central role in their responsibilities. Teen drivers need information about what their policy covers and excludes, and how choices such as vehicle types, deductibles, and driving habits could change their policy premiums.
How to Talk with Your Teen About Auto Insurance
A brief discussion can help give teens the power to try to avoid behavior-based premium increases and use their coverage wisely.
Explaining Insurance Coverage Types
Start with simple terms and definitions your teen might hear about as they begin learning about insurance. Coverage categories outline how a policy handles injuries, vehicle damage, and non-collision losses. Teens may benefit from learning how each one works.
 An insurance policy outlines coverage limits, deductibles, and claim procedures. You pay a fee called a premium to keep your coverage active.
 An insurance claim is a formal request you make to your insurance carrier for payment after a covered event like an accident or vehicle damage.
 A deductible is an amount you agree to pay with your own money before your insurance carrier contributes to help pay a portion of a covered claim.
 Liability coverage helps pay for injuries or property damage you may cause to other people in an accident; it does not pay to repair your own vehicle. States set minimum liability requirements, but families often choose higher limits for additional financial protection.
 Collision coverage helps pay to repair or replace your own vehicle if you hit another vehicle or object. The at-fault driver pays the deductible, and the insurance carrier covers the remaining repair costs.
 Comprehensive insurance coverage helps pay for damage to your vehicle caused by something other than an accident (think flooding, theft, hitting an animal).
 Uninsured/underinsured coverage can help provide financial protection if a driver is in an accident and the person who caused it (the at-fault party) is uninsured or doesn’t have high enough liability limits to fully cover the accident costs. Uninsured coverage may also cover hit-and-run accidents, in which the at-fault driver cannot be identified.
 Personal Injury Protection, sometimes called PIP or no-fault insurance, covers bills like medical expenses and lost wages if you’re hurt in a car crash, depending on your state’s laws. This coverage helps people get access to medical care, regardless of who is at fault.
 Roadside assistance can provide help when a vehicle breaks down and leaves the driver stranded. It may include coverage for a jump start, towing, lockouts, or tire changes. It’s important for teens to understand how to use this coverage, if available, during unexpected situations.
Teens should understand that insurance can provide some (but not all) financial protection and shouldn’t treat having insurance coverage as a replacement for safe driving.
Young drivers may feel more prepared when they understand how each part of their auto insurance coverage works.
Why Insurance is Important
Most states require drivers to carry minimum amounts of liability coverage. This coverage is not optional, and it can help support financial stability by covering the driver’s liability for third-party injuries and property damage after an accident or incident involving a vehicle.
Driving without the minimum required amount of auto insurance may result in penalties and fines, depending on state laws. Without appropriate insurance coverage, teens and their families risk paying out of pocket for the other party’s costs in an at-fault accident.
Maintaining an Auto Insurance Policy
It’s crucial to maintain valid auto insurance. Teens and their families must pay premiums on time, provide accurate information to the insurer, and follow state laws about coverage. The carrier must be informed of changes to drivers or vehicles within the household.
What Auto Insurance Doesn’t Do
An auto policy does not typically cover the following:
- Routine maintenance
- Damage due to normal wear and tear
- Mechanical breakdowns
- Accident costs exceeding the policy’s dollar limits
Tips for Choosing Appropriate Coverage
Families may compare insurance carriers when they search for the best auto insurance for new drivers. Teens can participate by reviewing coverage options and asking questions about limits and deductibles. They should understand that lower premiums may come with higher deductibles or reduced coverage.
Comparison shopping for competitive auto insurance can be tedious. Breathe Easy Insurance Solutions understands the challenges of finding affordable auto insurance. We can’t offer legal guidance, but we can find you a policy that protects you and your family without breaking the bank. Give us a call at (833) 786-0237.
Your Teen May Face Coverage Challenges
Young drivers may encounter higher premium costs because they lack driving experience. Insurance carriers often use age as a factor when determining premiums. Since new drivers haven’t spent much time behind the wheel they are statistically more likely to cause an accident, which is typically reflected in their risk profile. Teens should understand how driving experience and maintaining a clean driving record affect pricing.
Vehicle Type
The car your teen drives will likely impact premiums. Vehicles with a higher market value and repair costs, advanced technology, or strong performance features may trigger higher premiums. Older vehicles with lower repair costs may be a more economical choice.
If your teen drives a financed or leased vehicle, the lienholder can dictate insurance coverage to help touchprotect their financial interests in the event of an accident that damages the vehicle.
Carrier Requirements
Insurance carriers may request details about the vehicle, the teen’s license status, and the household’s driving history to help determine coverage options and set premiums.
Some carriers may choose not to insure teen drivers or not renew coverage for those with a history of traffic violations.
Policy Costs and Deductibles
Teens should understand how deductibles can affect premiums. In general, higher deductibles can reduce premiums, while lower deductibles can mean higher premiums. Be sure to evaluate whether the deductible is easily affordable if you must make a claim.
Penalties
Accidents, missed premium payments, and driving violations can lead to penalties. Depending on your state’s laws, these events may include higher premiums or policy cancellation and potentially impact your license status.
Teens should be made aware that responsible driving can help keep premiums affordable. Even a single moving violation or small at-fault accident can lead to much higher insurance costs.
How a Driver’s Behavior Impacts Auto Insurance
Safe driving habits can help reduce the risk of getting a traffic ticket or being involved in an accident. Safe driving can help keep insurance costs somewhat stable over time.
Carriers regularly evaluate driving behavior by checking driving records. Some insurance carriers ask drivers to provide access to real-time driving data, such as speed, hard braking, and the times when a teen is driving. This information, called telematics, can help set premiums.
Speeding
Speeding can increase the risk of an accident. Carriers typically raise premiums after a speeding ticket to reflect the risk of the driver causing an accident or filing a claim.
Distracted Driving
Many states have distracted driving laws, including “no-touch” cell phone laws designed to help reduce the risk of inattentive driving-related accidents.
Eating, having several peers in the vehicle, or focusing on music selection can also create a distracted driving incident. Accidents and tickets due to distracted driving can raise premiums.
Driving Under the Influence
Driving under the influence (DUI) of drugs or alcohol can create severe legal and financial consequences.
Carriers may impose significant rate increases or choose not to renew coverage after a DUI conviction. Boundaries must be set around substance use with teens, and they should be made aware of the potential consequences, including license suspension and fines.
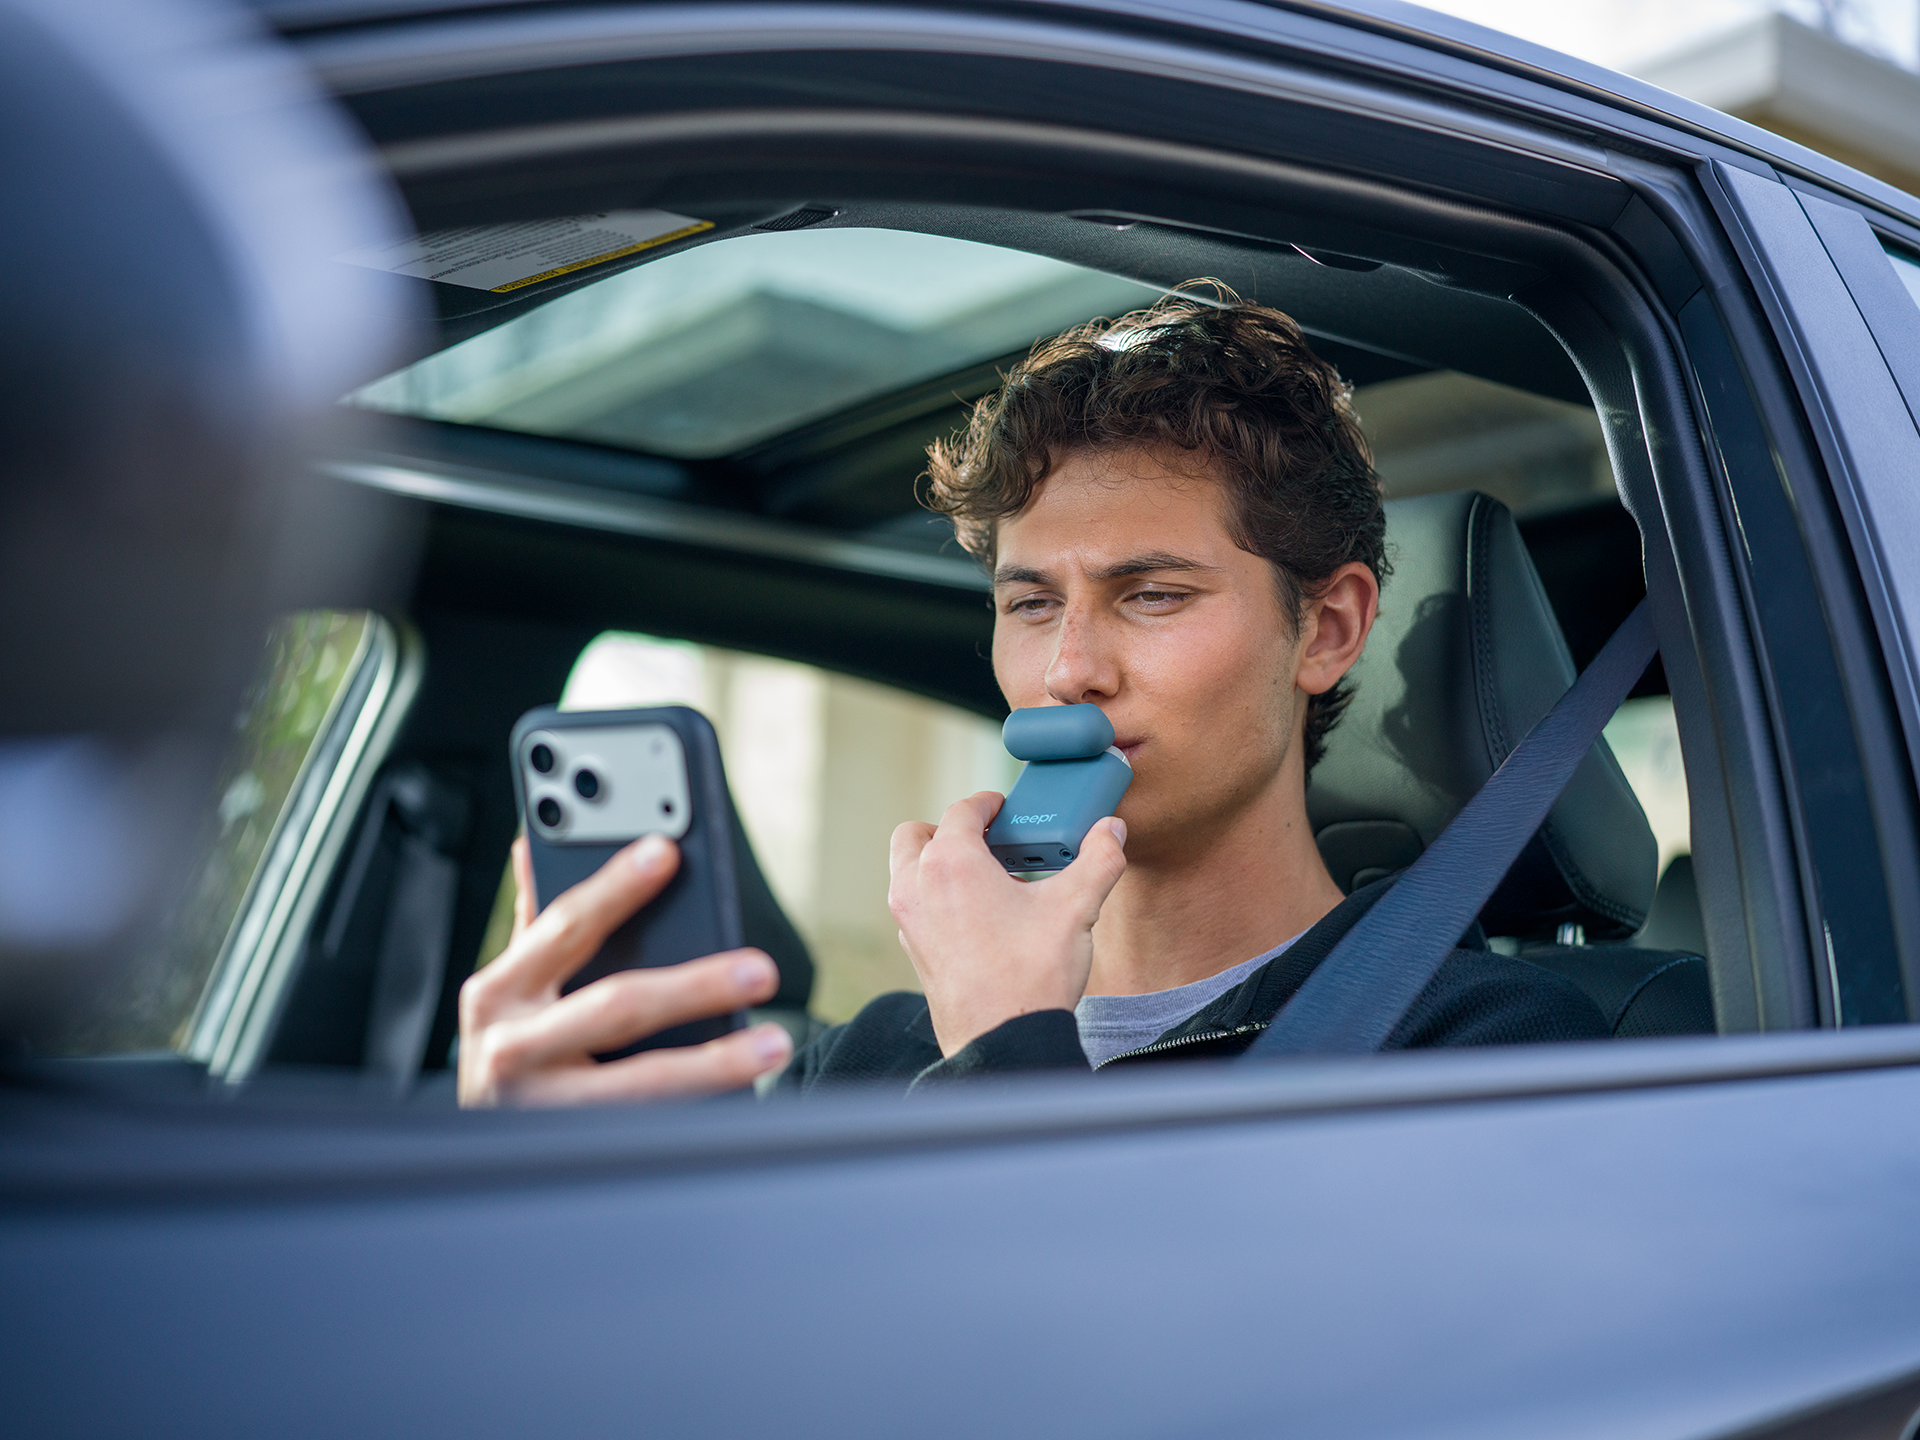
Some parents are introducing a way to determine if their new teen driver has been drinking to help reduce the chances of impaired driving. Keepr® offers a range of personal alcohol monitoring devices that can help you monitor alcohol consumption anytime, anywhere.
Keepr Drive is available in select U.S. markets.
Breathe Easy Insurance Solutions is part of the Mindr family of brands, which includes Intoxalock, DUI.org, and Keepr.
What Happens if There’s an Accident?
Teens should know how to respond in the event of an accident. Provide a checklist they can keep in the vehicle:
- Verify that all parties involved are uninjured and call for help if necessary.
- Report the incident to local police.
- Document the scene by taking pictures if it is safe to do so.
- Exchange contact and insurance information with the other driver if it’s safe to do so or let the police gather relevant information.
If you have specific questions about an accident, please consult an attorney. Breathe Easy can provide insurance related information, but we can’t provide legal guidance.
Breathe Easy Can Help You Find an Auto Insurance Policy for Your New Driver
Breathe Easy offers tools to help families review auto insurance coverage options, understand pricing, and evaluate policy features. Our Knowledge Center provides valuable resources to support informed decisions.
This informational blog is not legal advice. Always consult a qualified DUI attorney to assist with legal questions. If you have immediate questions about SR-22 insurance, call a Breathe Easy licensed insurance agent at (833) 786-0237.
FAQs: Auto Insurance for New Drivers
What should my teen know about auto insurance?
Teens should understand basic insurance terms, coverage types, your state’s legal requirements, and how their driving behavior can influence premium costs.
Will my teen pay more for auto insurance as a new driver?
New drivers may pay higher premiums, as carriers evaluate risk based on experience.
Can I put my teen on my auto insurance policy?
Many families add teen drivers to their existing auto insurance policy. Your insurance carrier can help you understand the details, such as whether they will cover teen drivers and the process of adding a teen driver to an existing policy.
Can I negotiate the deductible on my new driver’s auto insurance policy?
Families can choose from several deductible options, depending on their risk tolerance and budget.